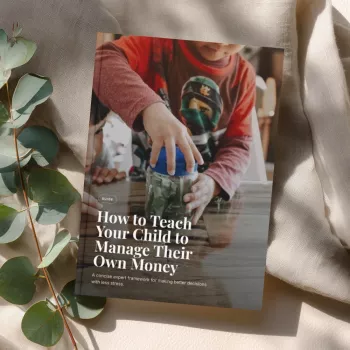
Money skills grow best when kids get small, real decisions—then a simple routine to follow. The goal is confidence: earning, choosing, saving, spending, and giving with clear boundaries and gentle accountability. Our team uses an age-by-age plan plus a few family rules that prevent daily arguments, and a simple system that makes progress visible without shaming mistakes.
The fastest way to reduce money friction is to make it predictable. Pick a weekly “money day” (10–15 minutes) where you review what came in (allowance or earned money), what went out, and what’s next. When kids know they’ll get a chance to talk about money regularly, they ask fewer “right now” questions at the worst moment.
Kids don’t need complex finance to start; they need real practice at the right size. Here’s a simple progression that keeps responsibility moving forward without overwhelming them.
| Age range | Skills to practice | What parents provide | What kids manage |
|---|---|---|---|
| 4–6 | Identify money, choose between options, wait to buy | Small cash amounts, a jar system, short goals | Spend decisions on small treats |
| 7–9 | Earn vs gift money, save for a goal, basic change | Simple chores/earning list, visual tracker | A weekly budget with Spend/Save/Give |
| 10–12 | Compare prices, plan for upcoming wants, track spending | A slightly bigger allowance, store comparisons | Personal categories (snacks, apps, small gifts) |
| 13–15 | Budget for events, avoid impulse buying, banking basics | Bank account support, spending boundaries | Monthly targets and a written plan |
| 16–18 | Paychecks, longer-term goals, credit concepts, contracts | Guidance on accounts, bills, and agreements | Work income budgeting and saving timeline |
If you want age-specific activities and prompts, the Consumer Financial Protection Bureau’s “Money as You Grow” is a strong, practical reference, and FDIC Money Smart for Young People is useful for structured lessons by age group.
Allowance works best when it’s a learning budget—not a prize and not a payment for being part of the family. Decide what it means in your house, then keep it consistent.
When you’re standing in a store aisle (or staring at an online cart), a short script beats a long lecture. We recommend three questions before buying:
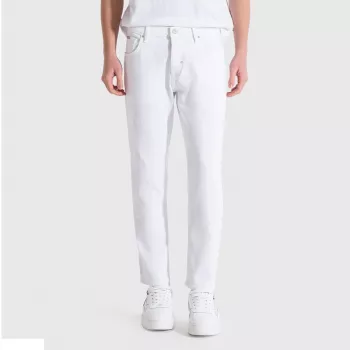
Saving feels more meaningful when it’s tied to real goals. For example, your child might save for a small gift for someone else (like 18K Gold Plated Daisy Drop Earrings) or practice budgeting for a higher-ticket target over time (like Ermanno Scervino Slim Fit Blue Jeans). The point isn’t the item—it’s learning to plan, wait, and follow through.
For families navigating in-app purchases and media spending, the American Academy of Pediatrics (HealthyChildren.org) has practical family guidance you can adapt into your house rules.
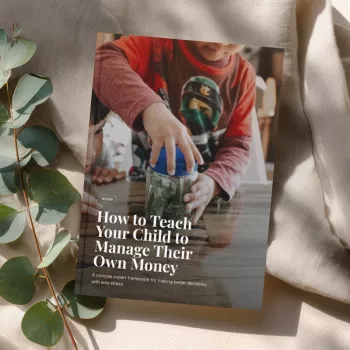
If you want a consistent system you can reuse every week (without reinventing the conversation), we recommend working from a structured guide with age-appropriate steps, simple routines, and conversation starters. Our in-stock resource, How to Teach Your Child to Manage Their Own Money, is designed to help your child take ownership without feeling overwhelmed—clear prompts, simple tracking, and repeatable weekly habits.
If your family likes goal-based learning, you can also turn “big household buys” into practice scenarios: set a shared target, research prices, and talk through trade-offs. Even something home-related like a Golden Ceramic Round Bathroom Sink can become a low-pressure lesson in comparing options and planning for a real budget.
Start as soon as your child can understand small choices—often around ages 4–6—with tiny amounts and clear Spend/Save/Give buckets. Increase responsibility as they show they can track money and wait for the next money day.
Keep core family responsibilities separate from paid tasks. Tie allowance to learning and age-appropriate responsibility, and offer optional paid jobs for extra earning so your child connects effort to income without making family contribution transactional.
Use a repeatable pause rule (like 24 hours for non-essentials), a fixed Spend bucket, and a short set of trade-off questions. Praise waiting and planning, and let the natural consequence happen when Spend runs out.
Leave a comment