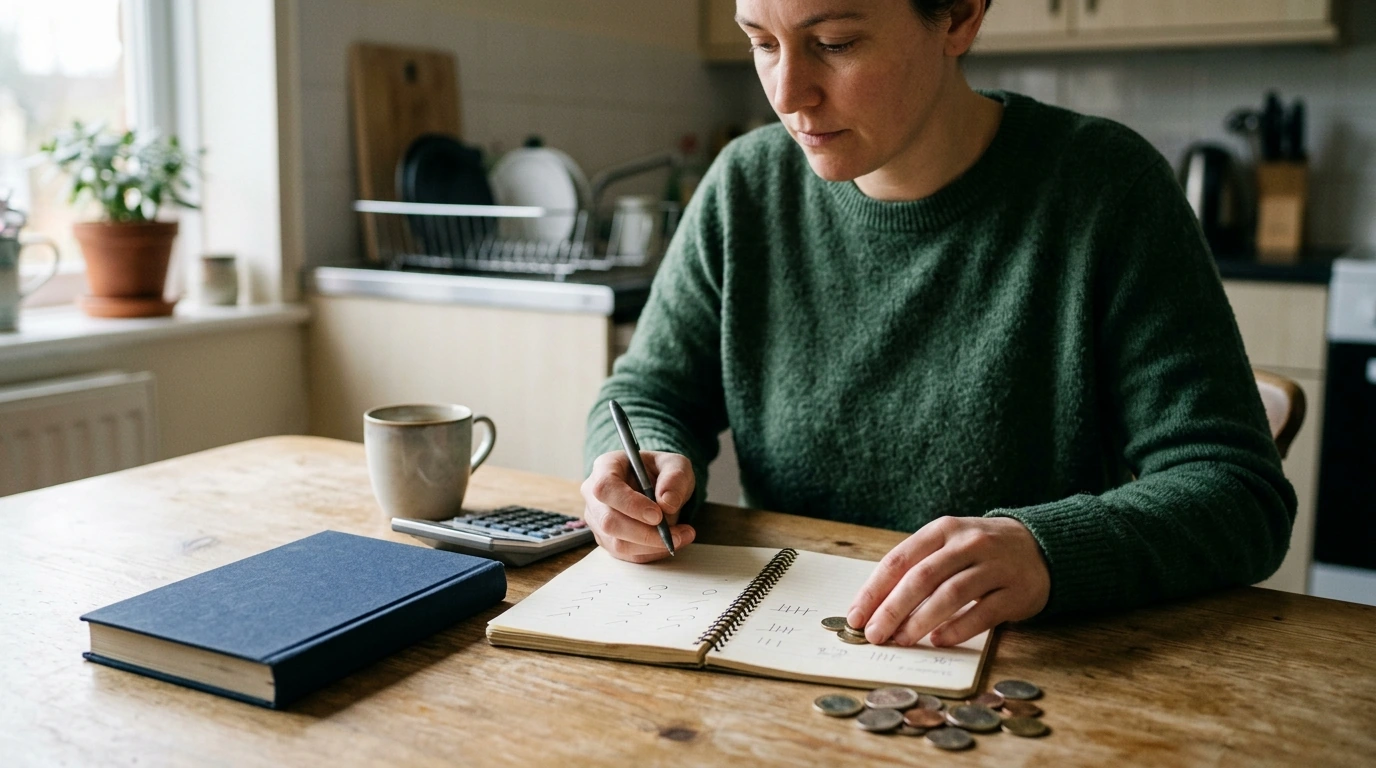
Money-mindedness is the habit of making clear, values-aligned financial choices—especially when emotions, social pressure, or scarcity thinking try to take over. A wealth-building mindset isn’t about being “good with money” overnight; it’s about repeatable behaviors: noticing patterns, setting systems, and choosing actions that compound over time. The goal is consistency you can sustain through busy weeks, surprise expenses, and shifting priorities.
Money-mindedness isn’t a personality trait. It’s a set of skills and defaults that make your financial life easier to steer.
When you think in systems, you spend less time negotiating with yourself and more time letting good defaults run in the background.
Most financial stress comes from the story playing in your head during a decision: “I’m behind,” “this won’t matter,” or “I’ll fix it later.” A wealth script is calmer and more practical: it favors actions you can repeat.
| Trap | What it sounds like | Replacement thought | Action to take today |
|---|---|---|---|
| All-or-nothing thinking | “If I can’t do it perfectly, why bother?” | “Progress beats perfection.” | Automate a small transfer to savings. |
| Lifestyle creep | “I deserve this upgrade now.” | “Earn more, then lock in a higher savings rate first.” | Increase savings by 1% before any upgrade. |
| Avoidance | “I’ll check later.” | “Numbers reduce stress when faced.” | Schedule a 15-minute money check-in. |
| Social comparison | “Everyone else is ahead.” | “Their highlight reel isn’t my plan.” | Unfollow one spending-trigger account. |
| Catastrophizing | “I’ll never catch up.” | “One step changes the trajectory.” | List 3 controllables (income, spending, skills). |
Money-minded people don’t rely on willpower. They set a few core habits that cover most scenarios.
If you want a structured set of prompts and exercises to make these habits stick, Money-Mindedness: Unlocking the Path to Financial Success – A Comprehensive Guide to Cultivating a Wealth-Building Mindset is a practical option to keep routines consistent when motivation dips.
A wealth mindset is built in small check-ins, not occasional “financial overhauls.” Keep it short enough that you’ll actually do it.
For credit fundamentals and what actually affects your score, the Federal Trade Commission’s credit score overview is a solid reference point.
Regret spending usually happens when decisions are made fast, emotional, or socially pressured. A few rules create a speed bump.
Planned splurges can still be meaningful. For example, if you set aside “fun money” and stick to it, a small purchase like 18K Gold Plated Daisy Drop Earrings can fit your plan without turning into a budget leak. Bigger lifestyle upgrades can work too—when they’re funded intentionally rather than financed impulsively, like saving toward a home refresh such as a Golden Ceramic Round Bathroom Sink.
To visualize how small, repeated contributions can grow, the Investor.gov compound interest calculator makes compounding feel concrete.
If you want straightforward budgeting frameworks and worksheets, the CFPB’s budgeting resources are a reliable starting point.
Awareness can improve in a week, but durable change typically shows up after 6–12 weeks of consistent habits like automated saving and a weekly check-in. The key is making the actions small enough to repeat even during stressful months.
Start a 10–15 minute weekly review, use simple spending categories, and automate “pay yourself first” transfers on payday. Fast improvement comes from reducing decision fatigue with defaults and a couple of clear rules.
No—money-mindedness includes intentional spending, risk protection (like emergency funds and insurance), income growth, and consistent investing. It can look like negotiating bills, avoiding high-interest debt, and building a diversified long-term plan.
Leave a comment